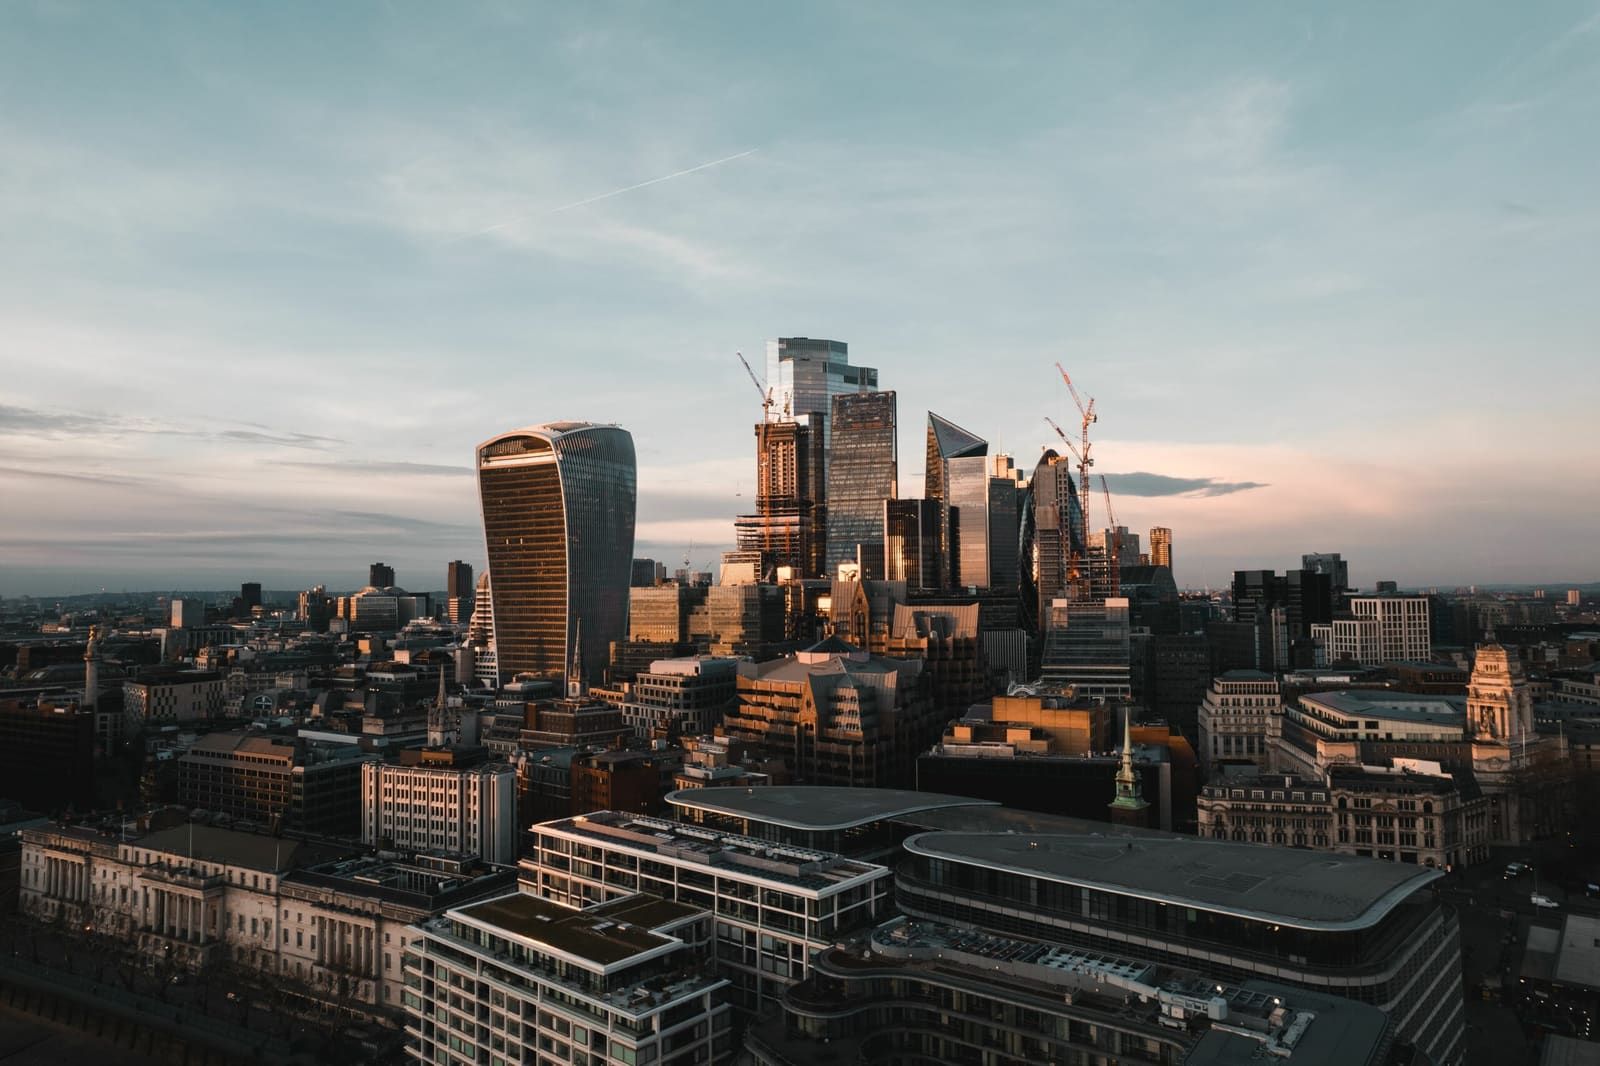
The June 2016 referendum represented the greatest structural shock to the City of London since the "Big Bang" reforms of the 1980s. For more than three decades, London had operated simultaneously as the United Kingdom's national financial centre, the de facto hub for European wholesale banking, and one of the principal nodes of global dollar finance. Brexit disrupted this hybrid position. The United Kingdom chose to leave the European Union's single market while attempting to preserve the benefits of regulatory proximity and market access that membership had previously guaranteed. Ten years after the referendum, the debate over financial Brexit has hardened into three competing narratives, none of which is fully established on empirical grounds.
The first is the resilience narrative. This thesis, advanced by certain constituencies within the City of London Corporation and supported by an increasingly substantial academic literature, holds that London retained its fundamental strengths despite Brexit (Bierbaum and Breen, 2025). Under this interpretation, the City remains dominant in foreign-exchange trading, the clearing of over-the-counter interest-rate derivatives and OTC derivatives more broadly (see Tables 1 and 2), international legal services, FinTech (see Table 3), and cross-border financial intermediation (Sarah Hall and Martin Heneghan, 2023, and Wójcik et al. 2024). Its proponents emphasise the "stickiness" of London's institutional ecosystem, while industry advocates point to the enduring strength of global financial-services exports, venture-capital investment, and financial foreign direct investment.
The second is the erosion narrative. More prevalent in Brussels, Frankfurt, and Paris — and increasingly visible within the City itself — this perspective stresses the slow but cumulative wearing-away of London's European position. New Financial estimates that more than 440 firms have transferred at least some of their activity to the EU27 since Brexit, with more than £900 billion in banking assets relocated. Amsterdam overtook London in European equity trading shortly after Brexit; Paris overtook London in stock-market capitalisation (see Table 4); and euro-denominated swap activity has migrated substantially to New York and continental Europe. Mainelli himself has suggested elsewhere that the cumulative employment impact could ultimately approach 40,000 jobs. The erosion argument is therefore not one of collapse but of gradual hollowing-out.
The third is the renaissance narrative. This interpretation holds that Brexit created an opportunity for regulatory reinvention. Through the Edinburgh Reforms, the Mansion House Reforms, and the Financial Services and Markets Act 2023, successive British governments have sought to build a more flexible, innovation-oriented, and internationally competitive regulatory framework. Its proponents argue that freedom from EU rules allows the United Kingdom to calibrate its regulation more finely to national strengths in FinTech, wholesale markets, green finance, and insurance. Yet three years after FSMA 2023, many of these claims remain aspirational rather than empirically demonstrated.
This article argues that all three narratives each capture part of a more complex structural transformation. Brexit neither destroyed the City nor left it unchanged. It rather reorganised European financial geography in an uneven and paradoxical way. The City lost the battle of fragmentation but won the battle of specialisation. London retained its dominance in the higher-value-added segments of international finance while ceding ground in more geographically mobile activities such as equity trading, initial public offerings (see Table 5), and parts of investment banking. At the same time, fragmentation across Paris, Frankfurt, Dublin, Amsterdam, and Luxembourg has prevented the emergence of a unified European rival to London.
The broader paradox is that the principal indirect beneficiary of Brexit may ultimately prove to be New York rather than the European Union. While the EU succeeded in relocating some financial activity from London, it has not created a consolidated European capital market capable of rivalling American financial depth and liquidity. In this sense, Brexit may have weakened both London's European role and the wider prospects for European financial autonomy.
01 | Three Narratives of Financial Brexit
1. The Resilience Narrative
Hall and Wójcik (2021) argue that London's resilience reflects the embeddedness of financial ecosystems. Financial centres depend not only on market access but also on deep institutional networks, legal expertise, labour-market density, linguistic advantages, time-zone positioning, and accumulated reputational capital. They stress the "functional, geographical, and institutional stickiness" of London's position in the global financial network.
The resilience interpretation emerged partly in reaction to early predictions that Brexit would trigger an exodus from the City of London. Before the referendum, estimates from consulting firms forecast tens of thousands of immediate job losses and large-scale migration of wholesale banking activity. Such scenarios did not fully materialise (Hall and Wojcik, 2021).
Empirically, several indicators support the resilience perspective. London remains the world's largest foreign-exchange trading centre according to data from the BIS Triennial Survey. The City also retains global dominance in OTC derivatives clearing, notably through LCH. London continues to attract substantial FinTech investment and remains Europe's largest venture-capital ecosystem for financial technology companies. The City also remains a major destination for international financial FDI.
The resilience perspective further notes that many of the activities relocated after Brexit were driven by regulatory necessity rather than strategic transformation. Banks created subsidiaries within the EU to preserve passport access, but much of the high-value decision-making and risk management often remained concentrated in London (Hall, 2025). The paradox reveals relatively modest job relocation despite the scale of institutional restructuring. The resilience narrative therefore holds that Brexit imposed adjustment costs without fundamentally displacing London's global financial centrality (Wojcik et al., 2024).
2. The Erosion Narrative
The erosion perspective acknowledges London's enduring importance but argues that Brexit nonetheless inflicted substantial cumulative damage. New Financial's annual "Brexit and the City" reports document more than 440 firms relocating operations, staff, or legal entities to the EU27. More than £900 billion in banking assets have been transferred from the United Kingdom to European subsidiaries. Frankfurt has established itself as the primary beneficiary for banking relocation; Dublin has strengthened its position in asset management (see Table 6) and fund domiciliation; Amsterdam has captured substantial trading-infrastructure activity; while Paris has consolidated its gains in asset management and insurance (Hall and Heneghan, 2021).
Several symbolic indicators reinforced the perception of decline. Amsterdam overtook London in European equity trading shortly after Brexit. Paris temporarily surpassed London in total stock-market capitalisation in 2022. Major companies have increasingly chosen New York over London for their initial public offerings, notably Arm and CRH. Euro-denominated swap trading has also shifted substantially to New York and EU venues.
Recent empirical work strengthens the argument that Brexit imposed significant long-term economic costs on the United Kingdom. Bloom et al. (2025), drawing on both macroeconomic simulations and firm-level survey data, estimate that "by 2025, Brexit had reduced UK GDP by 6–8%, with these effects accumulating gradually over time." They further conclude that business investment fell by 12–18%, while employment and productivity each declined by roughly 3–4% (Bloom et al., 2025). These effects are linked to prolonged post-referendum uncertainty, reduced market confidence, weaker demand, and inefficiencies in business management and resource allocation arising from protracted UK–EU negotiations.
These findings broadly align with more recent assessments from the Office for Budget Responsibility, which maintains that Brexit will leave British productivity approximately 4% lower in the long run than it would otherwise have been, primarily due to reduced trade intensity and weaker business investment. The cumulative impact of increased trade frictions, labour shortages, and declining investment has continued to weigh on the UK's growth performance well into the second half of the 2020s.
The erosion perspective further highlights the cumulative effects of regulatory uncertainty. Brexit weakened London's role as the natural European gateway for international capital. The end of passporting rights increased compliance costs and duplicated operational structures. ESMA and the ECB have also intensified pressure against "shell" subsidiaries and back-to-back booking models, encouraging more substantial relocation of staff and functions.
Kalaitzake (2022) argues that the structural interdependence between London and European markets slowed immediate fragmentation without eliminating the incentives for longer-term relocation. Similarly, Petit and Beck (2023) suggest that the EU's gradual strategy aims less at sudden repatriation than at long-term strategic autonomy. The erosion perspective therefore interprets Brexit not as a financial shock but as a slow attrition process whose full effects may not become visible for a decade or more (Ryan, 2023).
02. The Renaissance Narrative
The third interpretation sees in Brexit an opportunity for regulatory reinvention.
The Edinburgh Reforms of December 2022, extended by the Mansion House Reforms and the Financial Services and Markets Act (FSMA) 2023, constitute the most ambitious regulatory transformation programme undertaken by the United Kingdom since the post-financial-crisis reforms of 2008. They aimed to progressively replace the body of EU law retained in the British legal order after Brexit, strengthen national regulatory autonomy, and increase the international competitiveness of the British financial centre.
Key elements include reforms to Solvency II, ring-fencing, listing rules, prospectus requirements, and wholesale market regulation. The government also introduced a secondary competitiveness objective for the FCA and the PRA. Proponents argue that Brexit allows the United Kingdom to build a more proportionate and innovation-friendly regime, better suited to national economic priorities.
In their analysis, James and Quaglia (2023) deploy the concept of "differentiated de-Europeanisation" to distinguish several possible trajectories: deliberate divergence from the European framework, divergence resulting from inaction, attempted divergence that produced no effect, and areas where alignment with European rules has been maintained. For her part, Moloney (2024) examines the evolution of the UK's third-country regime and the gradual reconfiguration of the conditions of access to both the British and European markets since Brexit.
Yet the thesis of a City renaissance remains difficult to substantiate empirically. Many of the announced reforms have not yet been fully implemented, and those that have show limited effects so far. Above all, the competitiveness of a financial centre appears to rest more on structural factors — market depth, liquidity, talent concentration, and geopolitical influence — than on the degree of regulatory constraint alone. Critics also point out that excessive relaxation of rules could undermine financial stability without generating the anticipated growth gains. At this stage, the promise of post-Brexit renewal therefore remains more projection than established fact.
02 | Fragmentation and Specialisation
Brexit has, in fact, produced a paradox. By breaking with the single market, Brexit fragmented European finance while simultaneously reinforcing London's specialisation in the most globally integrated activities of international finance. The City thus lost some of its European functions while consolidating its role as a global hub.
This distinction is essential for explaining the consequences of Brexit sector by sector. London retained its dominant position in activities characterised by high liquidity, international network effects, and high relocation costs. This is notably the case for the foreign-exchange market (see Table 7), the clearing of OTC derivatives, institutional asset management, international legal services, and a large part of the FinTech ecosystem. These sectors rest on particularly powerful agglomeration economies that remain difficult to replicate elsewhere in the short term.
Conversely, London lost ground in activities whose development depends more heavily on direct access to the European market or on regulatory location requirements. These include spot equity trading, certain segments of investment banking, initial public offerings, and European insurance passporting. Brexit therefore did not produce a uniform outcome but a sectoral recomposition of European financial geography.
This redistribution of activities has, however, had an important consequence: it prevented the emergence of a single continental rival to the City. Gains were spread across several European financial centres. Frankfurt strengthened its role in banking supervision, investment banking, and market activities. Dublin established itself as a major centre for investment funds and aircraft leasing. Amsterdam attracted a significant share of trading activities and platforms. Paris consolidated its positions in insurance and asset management, while Luxembourg retained its central place in Europe-wide fund distribution. Ten years after the referendum, none of these cities has nonetheless managed to recreate, on its own, the integrated ecosystem that has been London's strength.
Howarth and Quaglia (2018) anticipated this dynamic early in the Brexit process, arguing that competition among member states would inhibit coordinated European financial consolidation. Subsequent developments have largely confirmed this prediction.
The EU's persistent difficulties in developing the capital markets union have further reinforced fragmentation. European capital markets remain segmented along national lines, with different insolvency regimes, pension systems, tax structures, and supervisory cultures. Brexit has therefore weakened London's European role without producing a commensurate strengthening of Europe's financial autonomy (see Table 8).
03| New York and the Geopolitics of Financial Power
The greatest long-term beneficiary of Brexit may ultimately be New York (Ryan, 2020).
This possibility received insufficient attention in the early Brexit debates, which focused primarily on competition between London and continental Europe. Yet several post-Brexit developments have reinforced New York's relative position within global finance (Ryan, 2018).
First, trading in euro-denominated derivatives migrated not only to the EU but also to American markets. Second, major global initial public offerings have increasingly favoured US venues owing to deeper liquidity, broader institutional investor bases, and higher valuations. Third, the reinforcement of dollar dominance following the return of geopolitical rivalry has strengthened New York's systemic centrality. The return of the Trump administration further intensified these dynamics. Geopolitical fragmentation, sanctions policy, and strategic competition have reinforced the importance of dollar liquidity networks and American capital markets. At precisely the moment when Europe was seeking greater financial autonomy, Brexit therefore fragmented the continent's most globally competitive financial ecosystem.
Brexit did not simply shift financial activity from London to a handful of European centres. It accelerated a redistribution of functions across the continent's financial landscape. The scale of this movement is now well documented. According to New Financial, more than 440 financial firms transferred to the European Union a portion of their activities, staff, assets, or legal structures following Brexit. The European Central Bank subsequently raised this estimate to nearly 500 firms. Bruegel estimates that approximately 10% of British banking sector assets and some 40,000 jobs have been relocated to the Union since 2016. However, these transfers were divided among Paris, Frankfurt, Dublin, Luxembourg, and Amsterdam rather than concentrating in a single financial centre capable of rivalling London (Hamre & Wright, 2021).
This dispersion of activities has prevented the emergence of a genuine European successor to the City. While London has lost some of its European functions, no continental centre has managed on its own to recreate the dense, integrated ecosystem that constitutes its strength. The result is therefore not the replacement of one dominant centre by another, but a lasting fragmentation of the European financial landscape.
In the meantime, New York has continued to strengthen its position at the summit of the global financial hierarchy. In the Global Financial Centres Index 39 published in March 2026 (see Table 9), the city once again occupied first place with a score of 767 points, ahead of London (766), Hong Kong, and Singapore (Z/Yen Group and China Development Institute, 2026). This development is all the more significant because the power of a financial centre rests on cumulative mechanisms: liquidity attracts investors, investors attract companies, companies attract financial intermediaries, talent, and capital. The United States thus continues to dominate global stock-market capitalisation, venture-capital financing, dollar liquidity, and investment-banking revenues — all factors that reinforce Wall Street's structural advantage (BIS, 2025).
The AFME 2025 report on capital markets union key performance indicators found that European IPO activity fell a further 23% in 2025, even as it grew significantly in the United States and major Asian markets (AFME, 2025). Recent cases such as Wise's announcement of its plans to transfer its primary listing from London to New York underscore the appeal of deeper American liquidity pools, broader institutional investor bases, and higher valuation multiples.
For capital-market access, the consequence is concrete: European and British companies are increasingly turning to US markets for large-scale equity financing, particularly in technology, fintech, biotechnology, and growth sectors. This may ease financing constraints for successful companies, but it also means that European savings pools, stock exchanges, and institutional investors play a smaller role in funding the expansion of European firms. The long-term effect is that the most internationally competitive European companies are progressively integrating more deeply into US-centred capital-market ecosystems (Wright et al., 2025).
As for the cost of financing, the effect is uneven. Large corporations can obtain cheaper equity in New York because of deeper liquidity, denser analytical coverage, and higher market valuations. But Europe, as a system, pays a structural cost. Fragmented markets, thinner domestic venture and growth-capital pools, and weaker IPO exit opportunities reduce the availability of risk financing across the continent.
The paradox is therefore profound. Brexit was partly justified in the name of sovereignty and national control (Ryan, 2021). Yet by further fragmenting European finance without giving rise to an alternative centre capable of competing with New York, it may have reinforced the dependence of both the continent and the United Kingdom on American financial infrastructure. This infrastructure is now far more than a mere economic support. Clearing systems, reserve currency, sanctions capacity, and capital-market depth now constitute instruments of power in their own right. Viewed from this angle, Brexit has not only weakened London's European role; it has also, potentially, reduced the collective capacity of Europe — including the United Kingdom — to compete in the financial and geopolitical contest with the United States.
The strategic question is therefore no longer whether Paris, Dublin, Amsterdam, or Frankfurt can each gain activity at the margin; it is whether Europe can build a sufficiently integrated capital markets union to prevent its companies, savings, listings, and financial infrastructure from gravitating increasingly around Wall Street rather than around a genuinely autonomous European financial system (Coben, 2026). Mario Draghi's 2024 report on European competitiveness further warned that fragmented capital markets limited Europe's capacity to finance innovation, defence, digitalisation, and the green transition (Draghi, 2024).
04 | Regulatory Divergence and Financial Sovereignty
The post-Brexit financial regulation debate also reveals a deeper tension between regulatory sovereignty and economic competitiveness. The British government presented the Financial Services and Markets Act (FSMA) of 2023 and its accompanying reforms as an opportunity to build a more flexible regulatory framework, better suited to national priorities (Beck et al.). Yet regulatory divergence is not in itself a competitive advantage. Everything depends on the value that financial actors attach to this flexibility relative to the benefits associated with European market access.
On this point, the signing in June 2023 of the memorandum of understanding on regulatory cooperation between the United Kingdom and the European Union constituted an attempt to stabilise post-Brexit relations. The Joint Financial Regulatory Forum has since met on several occasions, providing an institutionalised dialogue framework between the two parties. Progress remains limited, however. The equivalence regime remains piecemeal, revocable at any time, and considerably less protective than the passporting rights that financial institutions enjoyed before Brexit.
EMIR 3.0 simultaneously intensified the EU's efforts to reduce its dependence on British clearing infrastructure. Solvency II reforms have also diverged on either side of the Channel. These developments suggest that regulatory competition between the United Kingdom and the EU is likely to remain a structural feature of European finance.
At the same time, full divergence remains unlikely. The City's global role depends heavily on maintaining credibility, predictability, and compatibility with international standards. Excessive deregulation could undermine the institutional trust that underpins London's attractiveness. The reality is therefore one of constrained divergence. Brexit broadened British regulatory autonomy, but within the limits imposed by global financial integration. If an EU–UK post-Brexit relationship reset is to take place, these financial questions will need to be addressed (Berg et al., 2025).
Conclusion
Ten years after the referendum, the impact of Brexit on the City of London cannot be understood through simplistic narratives of collapse or triumph. The resilience narrative correctly identifies London's enduring strengths in globally interconnected financial activities. The erosion narrative accurately captures the cumulative relocation of activity, infrastructure, and institutional presence to the EU27. The renaissance narrative reflects genuine ambitions for regulatory reinvention, even if its long-term consequences remain uncertain (Table 10).
The City has not lost its global role, but it has lost its unchallenged European centrality. Brexit reorganised European financial geography in an uneven manner. London retained its leadership in high-value-added international finance while ceding ground in more geographically mobile activities. Meanwhile, fragmentation across Paris, Frankfurt, Dublin, Amsterdam, and Luxembourg has prevented the emergence of a unified continental rival.
The broader geopolitical consequence may be that New York has established itself as the principal financial beneficiary of Brexit. At a moment when Europe and the United Kingdom were seeking greater strategic autonomy, Brexit therefore weakened the continent's most globally integrated financial centre without creating a coherent alternative, reinforcing dependence on the United States.
Brexit has therefore not destroyed the City of London. It has transformed it — from the unchallenged financial capital of Europe into a more specialised global financial node, operating between a fragmented Europe and an increasingly dominant New York.
Table 1. OTC Interest-Rate Derivatives Trading (2025)
| Indicator | London / UK | EU Comparison | Interpretation |
|---|---|---|---|
| Daily OTC IRD turnover (April 2025) | USD 4.320 tn/day | Global market: USD 8.71 tn/day · Largest globally | London remains systemically important |
| Global market share (2025) | 49.6% | Largest EU centre: Germany (7.5%) · All EU combined: 13.8% · UK alone = 3.6x total EU | Brexit failed to displace London |
| 2022 UK market share | 42.9% | Eurex IRD grew +35% YoY in 2022 | Post-TCA dip; Eurex gains visible but limited |
| 2019 UK market share | 50.6% | No data available | Above pre-Brexit peak (49.9% in 2013) |
| Pre-Brexit peak (2013) | 49.9% | — | 2025 share: -0.3pp vs 2013 peak |
A. IRD by Instrument, UK Share (2025)
| Instrument | UK daily vol (USD bn) | UK global share (%) |
|---|---|---|
| FRAs | 438 | 61.0% |
| Swaps | 3,710 | 48.2% |
| OIS swaps | 2,875 | 50.8% |
| Other IR swaps | 834 | 40.9% |
| Options | 171 | 60.7% |
| Other instruments | 1 | 8.9% |
B. Top EU IRD Centres (2025)
| Country | Daily vol (USD bn) | Global share (%) |
|---|---|---|
| Germany | 0.7 | 7.5% |
| France | 0.3 | 3.7% |
| Spain | 0.1 | 0.9% |
| Netherlands | 0.1 | 0.8% |
| Denmark | 0 | 0.3% |
C. IRD UK Market Share Time Series
| Year | UK turnover (USD bn/day) | Global total (USD bn/day) | UK share (%) |
|---|---|---|---|
| 1998 | 122.9 | 343.6 | 35.8% |
| 2001 | 237.8 | 676.1 | 35.2% |
| 2004 | 563.0 | 1,330.5 | 42.3% |
| 2007 | 957.1 | 2,173.2 | 44.0% |
| 2010 | 1,234.9 | 2,648.9 | 46.6% |
| 2013 | 1,347.7 | 2,702.0 | 49.9% |
| 2016 | 1,180.2 | 3,039.0 | 38.8% |
| 2019 | 3,670.2 | 7,251.3 | 50.6% |
| 2022 | 2,359.4 | 5,501.8 | 42.9% |
| 2025 | 4,319.8 | 8,708.1 | 49.6% |
Table 2. OTC Derivatives Clearing Infrastructure
| Indicator | London | European Union | Strategic Meaning |
|---|---|---|---|
| LCH SwapClear Q4 2025 notional cleared | US$539 trillion(1) | — | London remains globally systemic |
| Q4 2025 trades cleared | 3.44 million(1) | — | Record clearing activity |
| EMIR 3.0 active-account rules | — | Implemented | EU pursuing strategic autonomy |
| Eurex clearing growth (2025) | — | +35% YoY(2) | EU building domestic capacity |
| Dependence on UK CCPs | High(3) | High(3) | EU still reliant on London |
Sources
- LCH, LCH SwapClear Q4 2025 Highlights (London: London Stock Exchange Group, 2026), accessed June 2, 2026, https://www.lseg.com/content/dam/post-trade/en_us/documents/lch/resources/lch-swapclear-q4-2025-highlights.pdf
- Eurex, "Full Year and December 2025 Figures at Eurex," news release, January 2026, accessed June 2, 2026, https://www.eurex.com/ex-en/find/news-center/news/Full-year-and-December-2025-figures-at-Eurex-4891494
- European Securities and Markets Authority (ESMA), EU Derivatives Markets 2023, ESMA Market Report ESMA50-524821-2930 (Paris: ESMA, 2023), accessed June 2, 2026, https://www.esma.europa.eu/sites/default/files/2023-12/ESMA50-524821-2930_EU_Derivatives_Markets_2023.pdf
Table 3. FinTech and Innovation Ecosystems
| Indicator | London / UK | European Union | United States |
|---|---|---|---|
| FinTech ecosystem strength | Europe's largest with almost half of EMEA fintech funding (2024); 53 unicorns(1) | Paris increasingly competitive(2) | Dominant(1) |
| GFCI 39 FinTech ranking | 5th globally(2) | No EU city in top 5(2) | New York 3rd(2) |
| Venture-capital scale | Strong but declining — UK fintech VC −27% to $9.9bn (2024), still #1 in Europe(3) | Fragmented(3) | Deep(3) |
| IPO exit opportunities | Weak relative to US — 18 listings (2024), lowest on EY record(4) | Weak — EMEA at 5-year low(5) | Deep and liquid — 218 IPOs, $33.6bn(5) |
Sources
- KPMG. 2025. Pulse of Fintech H2 2024. February 2025. https://kpmg.com/uk/en/media/press-releases/2025/02/uk-fintech-investment-hits-four-year-low-but-remains-european-leader.html
- Z/Yen Group and China Development Institute. 2026. The Global Financial Centres Index 39. London: Long Finance, March 26, 2026. https://www.longfinance.net/media/documents/GFCI_39_Report_2026.03.26_v1.1.pdf
- KPMG. 2026. Pulse of Fintech H2 2025. February 2026. https://assets.kpmg.com/content/dam/kpmgsites/uk/pdf/2026/02/pulse-of-fintech-global-analysis.pdf
- Ernst & Young (EY). 2025. "London Stock Market Ends 2024 on a High after Q4 Boost." EY UK, January 2025. https://www.ey.com/en_uk/newsroom/2025/01/london-stock-market-ends-2024-on-a-high-after-q4-boost
- World Federation of Exchanges (WFE). 2025. FY 2024 Market Highlights. February 10, 2025. https://wfe-live.lon1.cdn.digitaloceanspaces.com/org_focus/storage/media/Cally%20Billimore/WFE%20FY%202024%20Market%20Highlights%20Report%2010022025.pdf
Table 5. IPO and Listings Competitiveness
| Indicator | London / UK | European Union | United States |
|---|---|---|---|
| IPO market condition (2025)(1) | Rebounding — strongest year since 2021 | Declined | Strong recovery |
| Attraction for growth firms | Weakening | Fragmented | Increasingly dominant |
| Deep liquidity pools | Moderate | Limited | Very high |
| Cross-border listings appeal | Reduced | Weak | Very strong |
| European firms shifting toward US markets (2015–24)(2) | 51 UK firms / $272bn but ~90% of IPOs stay domestic | 130 European firms (not just EU) / $676bn — just 2% of listed firms, 4% of value | Net beneficiary, though the pull might be overstated |
Note on "European firms shifting toward US markets": New Financial / HSBC Global Research (2025) identified 130 European companies (UK, EU, Switzerland, Norway, Iceland) that moved their primary US listing over 2015–24, worth a combined $676bn at the time of the move — of which 51 UK firms ($272bn). The report finds the trend more pronounced than expected yet less concerning than thought, calls the "exodus" narrative overblown, and notes 70% of the movers trade below their listing price. It identifies the public-to-private shift (>1,000 European delistings, >$1tn) as a far bigger threat. Counterpoint: the ECB (2024)(3) finds M&A, not transatlantic flight, is the primary driver of European delistings.
Sources
- Anani, Karim. 2025. EY Global IPO Trends 2025. Ernst & Young, December 17, 2025. https://www.ey.com/en_pt/insights/ipo/trends
- Wright, William, James Thornhill, Christopher Breen, and Matilda Hames. 2025. A Reality Check on International Listings. London: New Financial, in partnership with HSBC Global Research, April 2025. https://www.newfinancial.org/reports/a-reality-check-on-international-listings
- European Central Bank (ECB). 2024.
Table 6. Institutional Asset Management
GTPO Comment: Figures reconciled to EFAMA, ICI and IA primary sources; the "Europe" column (€33.7tn) is measured by management location and includes the UK and Switzerland, so it overlaps the UK column and the two should not be summed.
| Indicator | London / UK | Europe (incl. UK & Switzerland) | United States |
|---|---|---|---|
| Position in Europe | Largest ecosystem | Large but fragmented | Global leader |
| AuM 2024(1) | €12.1tn — Major share of €33.7tn market | €33.7tn | US managers globally dominant |
| AuM Q3 2025(1) | No figure yet | €34.4tn est. | Not published yet |
| Share of global regulated fund assets (by domicile, Q2 2025)(2) | 2.8% | 30.9% global share | 51.7% global share |
Sources
- European Fund and Asset Management Association (EFAMA). 2025. Asset Management in Europe: An Overview of the Asset Management Industry. 17th ed. Brussels: EFAMA. https://www.efama.org/sites/default/files/files/asset-management-report-2025-v3_0.pdf
- European Fund and Asset Management Association (EFAMA) and Investment Company Institute (ICI). 2025. International Statistical Release: Worldwide Regulated Open-End Fund Assets and Flows, Second Quarter 2025. Brussels: EFAMA. https://www.efama.org/sites/default/files/files/international-statistical-release-q2-2025.pdf
Table 7. Global Foreign Exchange Trading (2025)
GTPO Comment: Table 2 unpacks global foreign-exchange trading in 2025 across four views: (A) the headline London–EU comparison from the BIS Triennial Survey, (B) the UK's share broken down by instrument, (C) the leading EU FX centres, and (D) the UK's market-share time series since 1989.
A. Global FX Trading (2025) | BIS Triennial
| Indicator | London / UK | EU Comparison | Interpretation |
|---|---|---|---|
| Daily FX turnover (April 2025) | USD 4.74 tn/day | Global market: USD 12.56 tn/day | London is the world's largest FX centre |
| Global market share (2025) | 37.8% | Largest EU centre: Germany (3.1%) · All EU combined: 8.7% · UK alone = 4.3x total EU | Brexit did not displace London |
| 2022 UK market share | 38.0% | — | Post-TCA dip — since recovered |
| 2019 UK market share | 43.2% | — | Above pre-Brexit peak (2013) |
| Pre-Brexit peak (2013) | 40.8% | — | 2025 share: -3.0pp vs 2013 peak |
B. FX by Instrument, UK Share (2025)
| Instrument | UK daily vol (USD bn) | UK global share (%) |
|---|---|---|
| Spot transactions | 1,418 | 37.9% |
| Outright forwards | 1,042 | 46.8% |
| FX swaps | 1,809 | 32.4% |
| Currency swaps | 97 | 48.1% |
| Options | 376 | 46.7% |
| Other instruments | 0 | 0.0% |
C. Top EU FX Centres (2025)
| Country | Daily vol (USD bn) | Global share (%) |
|---|---|---|
| Germany | 0.4 | 3.1% |
| France | 0.2 | 1.9% |
| Denmark | 0.1 | 0.8% |
| Luxembourg | 0.1 | 0.6% |
| Spain | 0.1 | 0.5% |
D. FX UK Market Share Time Series
| Year | UK turnover (USD bn/day) | Global total (USD bn/day) | UK share (%) |
|---|---|---|---|
| 1989 | 187.0 | 743.7 | 25.1% |
| 1992 | 297.2 | 1,115.5 | 26.6% |
| 1995 | 478.8 | 1,632.7 | 29.3% |
| 1998 | 685.2 | 2,099.4 | 32.6% |
| 2001 | 541.7 | 1,704.7 | 31.8% |
| 2004 | 835.3 | 2,608.1 | 32.0% |
| 2007 | 1,483.2 | 4,281.1 | 34.6% |
| 2010 | 1,853.6 | 5,045.3 | 36.7% |
| 2013 | 2,726.0 | 6,685.7 | 40.8% |
| 2016 | 2,406.3 | 6,513.5 | 36.9% |
| 2019 | 3,576.4 | 8,279.5 | 43.2% |
| 2022 | 3,735.1 | 9,823.2 | 38.0% |
| 2025 | 4,742.6 | 12,557.1 | 37.8% |
Source: BIS Triennial Central Bank Survey, various years (1989–2025)
Table 8. Capital-Market Depth and Corporate Finance
| Indicator | United Kingdom | European Union | United States |
|---|---|---|---|
| Market-based finance share | Stronger than EU average – risk capital >10% of SME funding vs 2–5% in EU(3) | 13% of corporate funding (2025)(1) | Dominant model — bank lending only ~45% of corporate debt, vs 85% in EU(2) |
| Capital-market funding / GDP | Significant | 3% of GDP(1) | 8% of GDP(1) |
| Financial structure | Mixed bank/market system | Bank-dominated with bank lending ~85% of corporate debt vs 45% US(2) | Deep equity and bond markets — bank share ~45%(2) |
| Strategic implication | International orientation | Structural fragmentation | Major global advantage |
Sources
- Association for Financial Markets in Europe (AFME). 2025. Capital Markets Union: Key Performance Indicators. Press release, "Slow Growth in Europe's Capital Markets, Competitiveness Gap Remains," November 26, 2025. https://www.afme.eu/news-insights/press-releases/slow-growth-in-europe-s-capital-markets-competitiveness-gap-remains/
- Farah, Elie, Matt Strahan, and Ryan Lancaster. 2026. "Europe Has the Capital to Compete — It Just Needs to Fix Its Financial Plumbing." World Economic Forum, January 20, 2026. https://www.weforum.org/stories/2026/01/europe-has-capital-to-compete-just-needs-fix-financial-plumbing/
- World Economic Forum. 2024. "How Capital Market Finance Can Boost European Businesses." March 2024. https://www.weforum.org/stories/2024/03/how-capital-market-finance-boost-european-businesses/
Table 9. Global Financial Centre Rankings (2026)
| Financial Centre | Global Rank | GFCI Score | Primary Competitive Strength |
|---|---|---|---|
| New York | 1 | 767 | Global capital markets and dollar liquidity |
| London | 2 | 766 | FX, derivatives, international finance |
| Hong Kong | 3 | 765 | China gateway and Asian capital markets |
| Singapore | 4 | 764 | Asian wealth and trading hub |
| Frankfurt | 15 | 734 | ECB supervision and wholesale banking |
| Luxembourg | 16 | 733 | Cross-border funds |
| Paris | 19 | 730 | Banking, insurance, asset management |
| Amsterdam | 20 | 729 | EU trading infrastructure |
Source: Z/Yen Group and China Development Institute. 2026. The Global Financial Centres Index 39. London: Long Finance, March 26, 2026. https://www.longfinance.net/media/documents/GFCI_39_Report_2026.03.26_v1.1.pdf
Table 10. Comparative Balance of Financial Strengths
| Sector | London | European Union | United States / New York | Brexit Outcome |
|---|---|---|---|---|
| Foreign exchange | Very strong | Fragmented | Strong via dollar system | London resilient |
| OTC derivatives | Very strong | Growing via Eurex | Strong | London specialised |
| Clearing infrastructure | Dominant | Strategic push underway | Strong | EU still dependent |
| Asset management | Strong | Luxembourg/Dublin/Paris gains | Dominant globally | US scale advantage |
| IPOs and listings | Weakening | Weak | Very strong | US major beneficiary |
| Equities trading | Reduced EU role | Amsterdam gains | Strong | Partial EU success |
| Banking balance sheets | Important | Frankfurt/Paris strengthened | Very strong | Fragmented relocation |
| FinTech | Strong | Improving | Dominant scale finance | UK competitive but constrained |
| Financial exports | Very high | Fragmented | Globally dominant | London still global |
| Strategic autonomy | Reduced EU gateway role | Incomplete CMU | Strengthened | Brexit indirectly favours US |
Source: GTPO synthesis of Tables 1–9
Bibliography
- AFME, "Capital Markets Union Key Performance Indicators", 8th Edition. Association for Financial Markets in Europe. Brussels, 2025
- Bank for International Settlements, "Triennial Central Bank Survey of Foreign Exchange and OTC Derivatives Markets", Basel, 2025.
- Jesper Berg, Rebecca Christie, Hans Geeroms and Francesco Papadia, "Make finance part of the EU-UK post-Brexit reset", Bruegel Analysis, 29 April 2025
- Maximilian Bierbaum and Christopher Breen, The Interconnectedness of EU and UK Financial Markets, New Financial, December 2025
- Nicholas Bloom, Philip Bunn, Paul Mizen, Pawel Smietanka and Gregory Thwaites, "The Economic Impact of Brexit", NBER working paper, November 2025
- Craig Coben, "The outlook for IPOs in 2026: oversized and over there", Financial Times, 6 January 2026
- Mario Draghi, "The Future of European Competitiveness", Report for the European Commission, Brussels, September 2024.
- Eurex, "Full Year and December 2025 Figures at Eurex", Deutsche Börse Group, 2026
- Sarah Hall and Martin Heneghan, "Brexit and 'missing' financial services jobs in the UK", Vol. 18, No. 2, 235–249, 2023. Contemporary Social Science.
- Sarah Hall "Where Next for UK Financial Services Post Brexit?", Border Crossing, 15(3):121-126, June 2025
- Sarah Hall and Dariusz Wojcik, "'Ground Zero' of Brexit: London as an international financial centre", Geoforum, vol. 125, p.195-196, 2021
- Sarah Hall and Martin Heneghan, "The emerging geography of European financial centres: Fragmentation in the European Union and concentration in the UK?", European Urban and Regional Studies, vol. 28, issue 1, p.40-46, 2021
- Eivind Friis Hamre & William Wright, "Brexit & The City: The Impact So Far", New Financial, April 2021
- David Howarth and Lucia Quaglia, "Brexit and the battle for financial services", Journal of European Public Policy, 25(8), 2018
- Scott James and Lucia Quaglia, "Brexit, the City and the Contingent Power of Finance", New Political Economy, 24(2), 258-271, 2019
- Scott James and Lucia Quaglia, "Differentiated de-Europeanisation: UK policymaking in finance after Brexit", Journal of European Public Policy, Volume 30, Issue 11 2023
- Manolis Kalaitzake, "Resilience in the City of London: the fate of UK financial services after Brexit", New Political Economy, 27:4, 610-628, 2022
- LSEG LCH, SwapClear Q2–Q4 2025 Highlights. London Stock Exchange Group, 2025
- Niamh Moloney, (2024), "Access to the UK Financial Market After the UK Withdrawal from the EU: Disruption, Design, and Diffusion", European Business Organization Law Review. 25(1), 25-47, 2024
- Christy Ann Petit and Thorsten Beck, "Recent trends in UK financial sector regulation and possible implications for the EU, including its approach to equivalence", European Parliament, Policy Department for Economic, Scientific and Quality of Life Policies Directorate-General for Internal Policies, February 2023
- John Ryan, "Passporting remains best option for UK financial services industry post-Brexit or New York may have last laugh", LSE Brexit Blog, 2018
- John Ryan, "Brexit to China? If forced, London will choose Washington over Beijing", LSE Brexit Blog, 2020
- John Ryan, "Brexit and Covid-19 Combined Undermine Britain's Global Influence", Irish Studies in International Affairs, 2021
- John Ryan, J. (2023), "How Brexit Damaged the United Kingdom and the City of London", The Economists' Voice, 20(2).
- Dariusz Wojcik, Stefanos Ioannou and Panagiotis Iliopoulos, "The City of London after Brexit: Sticky power in the Global Financial Network" Progress in Economic Geography 2 (2024)
- William Wright, James Thornhill, Christopher Breen & Matilda Hames, "A reality check on international listings", New Financial, April 2025
- Z/Yen Group and China Development Institute, "The Global Financial Centres" Index 39", Long Finance, London, 2026